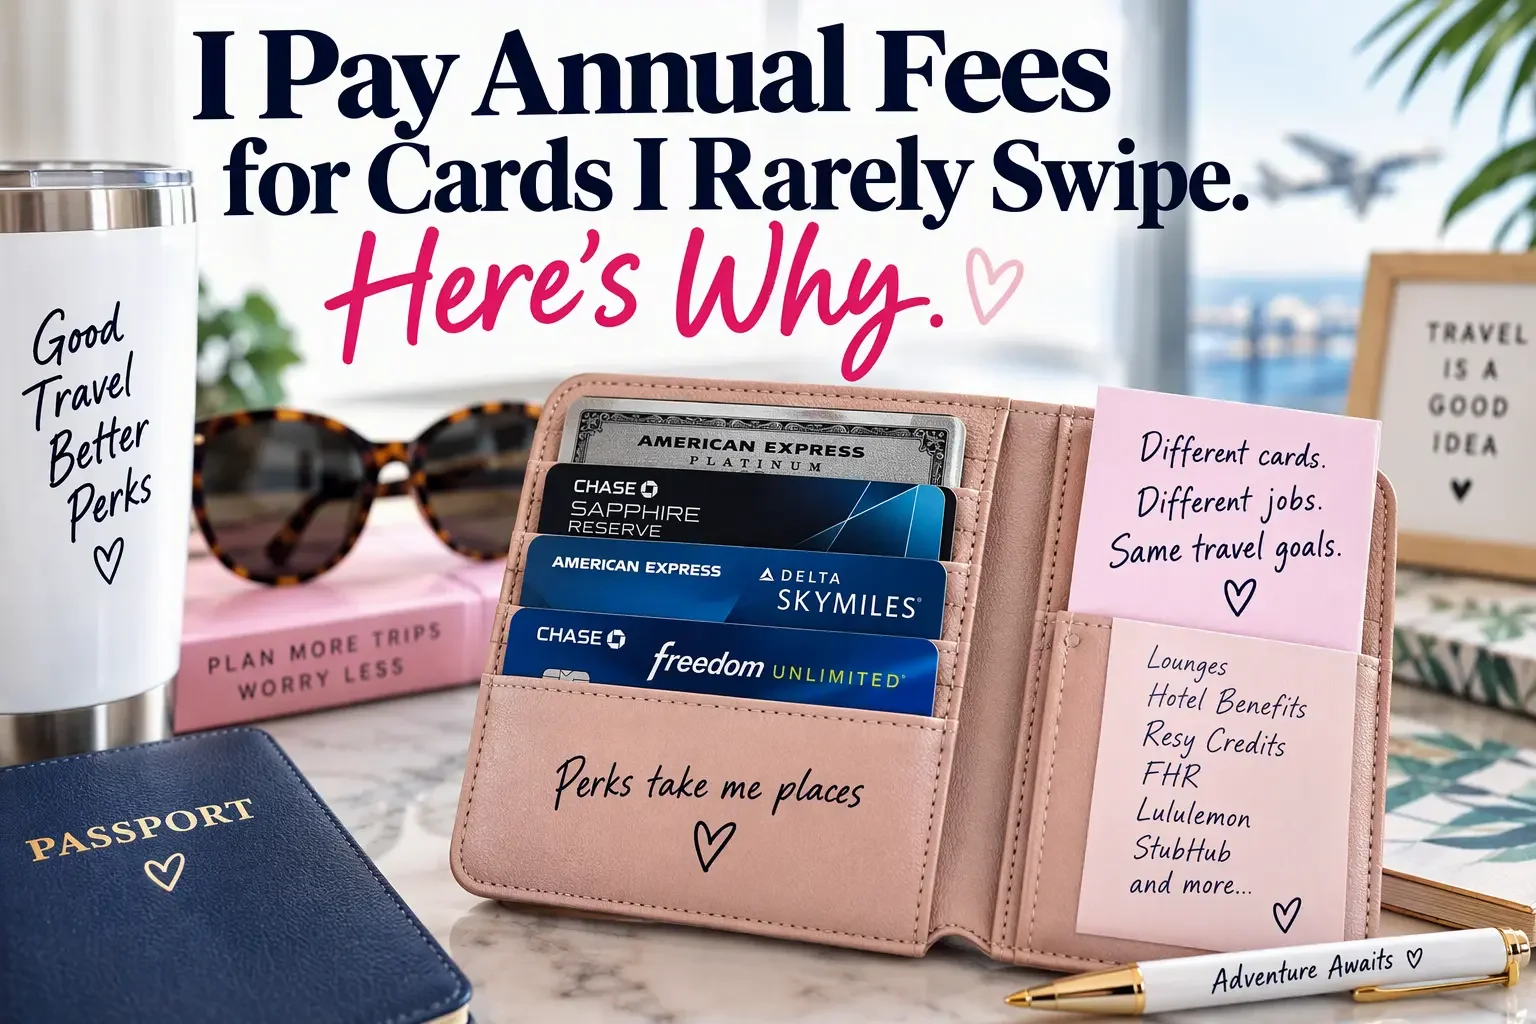
I have a wallet full of expensive credit cards that rarely see the light of day.
And I'm perfectly happy about it. 😂
Because here's something that gets lost in all the talk about which credit card is "best":
Some of my favorite cards aren't my everyday cards at all.
I don't need every card to earn the most points on groceries, dinner, and random Target runs.
Some of them have a completely different job.
Personal Referral & Affiliate Link Disclosure: I am not a credit card affiliate. Some credit card links in this post may be my personal referral links, which means I may receive points, miles or another referral bonus if you use one. This post may also contain affiliate links for other products or services, which means I may earn a commission at no additional cost to you. As always, I only share what I actually use, like or think is worth knowing about.
This is my personal experience, not individualized financial advice. Credit profiles and financial situations vary.
New to points and miles? My Beginner Credit Card Guide is a good place to start before diving into how I manage a much bigger wallet.
I Love My Amex Platinum. I Just Don't Use It Every Day.
My Amex Platinum review will tell you I'm a big fan of this card.
But am I pulling it out for every random purchase?
Nope.
For most purchases, I'm only earning one point per dollar. I have better cards for everyday spending.
But send me on a trip and suddenly the Platinum gets very busy.
I use the airport lounge access. I use my Resy credits. I use Fine Hotels + Resorts. And yes, I am absolutely using that lululemon credit. 😂
Next week is actually a perfect example.
We're staying at the Conrad Fort Lauderdale, where I'll be putting my Platinum benefits to work. Then, on the way home, we'll be at FLL using the airport lounge benefits.
That's why I have this card.
It doesn't need to buy my groceries too.
My Chase Sapphire Reserve Has a Job Too
My Chase Sapphire Reserve review works much the same way.
For everyday, non-bonus spending, I'm much more likely to grab my Chase Freedom Unlimited.
But when I'm booking a trip?
The Reserve comes out.
I use it for travel, and then there are the perks I actually use, including restaurant benefits and StubHub credits.
So once again, I have a card I love and happily keep that isn't necessarily the card I'm reaching for every Tuesday afternoon.
And that's okay.
I Don't Measure a Perk Card by How Often I Swipe It
This is probably the biggest difference between how I look at my everyday cards and my perk cards.
For an everyday card, I care a lot about what I'm earning when I use it.
For a perk card, I'm asking a different question:
Did the benefits I actually used outweigh what it cost me to keep the card?
Not the giant list of benefits on the website.
Not the theoretical value if I somehow managed to use every single credit.
What did I actually use?
That's the number I care about.
And Every One of These Cards Gets Reevaluated
No card has a lifetime appointment in my wallet.
Every year, I look at these cards again.
Am I still using the benefits?
Do they still fit how I'm traveling?
Would I have spent that money anyway?
Does another card now give me something similar?
And ultimately:
Would I pay this annual fee again today?
Sometimes the answer is an easy yes.
Sometimes it's not.
That's how I ended up cancelling a credit card instead of downgrading it.
The card had stopped earning its job in my wallet.
Meanwhile, I've also kept a completely boring 25+ year-old no-fee Delta card that gets one little bill every month and basically exists because it's old. 😂
Different cards. Different jobs.
My Wallet Has to Work for My Real Life
This is probably the part of credit-card strategy I care about the most.
I'm not changing my life to justify keeping a credit card.
If I naturally use the perks and they give me more value than I'm paying for the card, great.
If I find myself buying things I don't really want just so I can say I "used the credit," that's not savings.
And if the math stops working?
The card doesn't automatically stay just because I used to love it.
That's why some of the most expensive cards in What's In My Wallet can sit there quietly for weeks and still absolutely earn their place.
They don't need to do everything.
They just need to do their job.
About the Author
Julie Davis is the creator of No Point Left Behind, where she shares the points, miles, credit cards, cruises and travel perks she actually uses in real life. She's been navigating credit cards and rewards for more than 20 years, with a philosophy that's pretty simple: understand what you're paying for, use the benefits that fit your real life and reevaluate when they don't.
Want to keep the conversation going? Follow No Point Left Behind on Facebook or join the No Point Left Behind Facebook community for more real-life travel, points and credit-card conversations.
