Personal Referral Link Disclosure: I am not a credit card affiliate and I am not paid to recommend specific credit cards. Some links in this post may be my personal referral links. If you choose to apply through one of those links, I may receive points, miles or another referral bonus. My opinions and recommendations are always based on my own experience.
This is my personal experience, not individualized financial advice. Credit profiles and financial situations vary.
Spoiler alert: it's not for the points or the perks.
I have credit cards I use for points, cards I keep for travel perks, and cards that get most of my everyday spending.
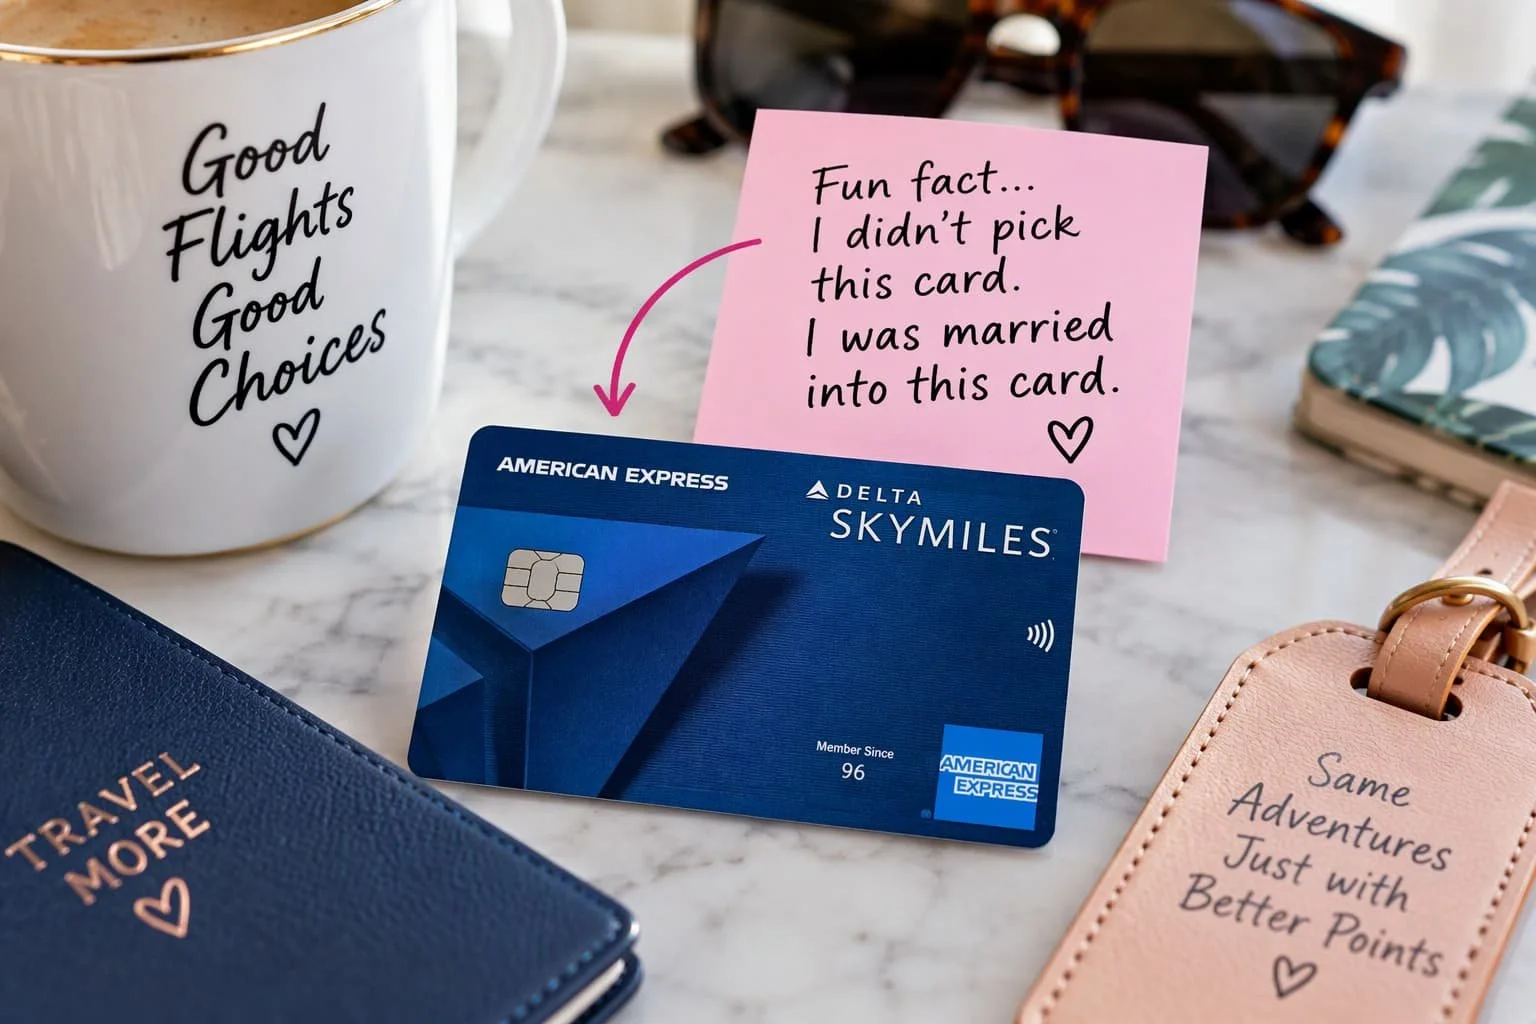
And then I have my Delta SkyMiles Blue American Express Card.
This account has been in our lives for more than 25 years.
Fun fact: I didn't even pick it. I married into it. 😂
Today, we have one bill automatically charged to it every month. We pay it off every month, and I fully expect we'll continue doing exactly that forever.
Here's how much I care about maximizing this particular card:
Until I started writing this post, I couldn't have told you how many miles it earns per dollar.
That's because the points aren't why I keep it.
Its Job Is Basically to Be Old
I think every credit card in my wallet needs a job, but those jobs aren't always the same.
Some earn points. Some come with perks. Some get my everyday spending.
This one?
Its job is basically to be old.
There's no annual fee, I've had the account for more than 25 years, and it represents a long piece of my credit history.
So we put one recurring bill on it, pay it every month, and otherwise leave it alone.
Not every credit-card strategy has to be complicated.
But Didn't I Just Cancel a Credit Card?
Yep.
I recently shared why I cancelled a credit card instead of downgrading it, and that's exactly why I wanted to tell this story too.
Keeping this card doesn't contradict that decision.
The card I cancelled no longer had a job that made sense for me.
This one does.
I'm not a fan of blanket rules like never cancel a credit card or always keep your oldest card.
I'd rather ask:
What is this card doing for me?
In this case, it's a no-fee account I've had for decades. I have no compelling reason to get rid of it.
So I don't.
It Also Changed How I Thought About My Son's First Card
When my oldest son, Finn, was getting started, I recommended he look at the Chase Freedom Unlimited.
My thinking wasn't about chasing the biggest welcome bonus.
It was much simpler:
Your first card could potentially be with you for a very long time.
That's one reason I liked the idea of starting with a no-annual-fee card that could still have a place in his wallet years from now.
If you're just getting started, you can find more of my beginner credit-card and points guides here.
Every Card Doesn't Need to Be Exciting
My Delta Blue isn't one of my favorite cards for everyday spending.
It isn't one of my favorite cards for travel perks.
Honestly, I had to look up what it earns.
But I still have a reason for keeping it.
That's really the point.
You can see what's currently in my wallet and why I keep each card, but you'll notice something interesting: the cards I use for everyday spending and the cards I keep for perks aren't necessarily the same.
That's another story for another day.
For now, my boring old Delta card has a job. It costs me nothing to keep. We give it its one little bill every month and pay it off.
And after 25+ years together, apparently we're committed.
The old girl can stay. 😂
About the Author
Julie Davis is the creator of No Point Left Behind, where she shares the real-life strategies she uses for points, credit cards, cruises and travel. Her philosophy is simple: understand your options, do the math and use the strategies that actually work for your life.
